Is Policy Era a Legitimate Insurance Platform? An Honest and Uncensored Analysis Before You Purchase
A Policy Era insurance guide showing a customer reviewing insurance online, with visual indicators for IRDAI registered insurers, data privacy, claim support, and a transparent insurance process.
Before you purchase or renew your insurance policy such as a health shield, term life cover or motor policy, there's a lot of uncertainty in your mind.
In a world where insurance products are marketed aggressively through various comparison websites, automated comparison portals and unsolicited tele-callers who promise unrealistic lower premiums, it is natural to wonder if Policy Era is genuine.
This guide will analyze if Policy Era insurance platform is legitimate or not.
Is Policy Era a legitimate Insurance Portal?
Yes, it is. Policy Era is a legitimate insurance consultation, comparison and advisory platform working within the Indian insurance regulatory framework.
In contrast to generic web crawlers or lead generators selling your phone number to 30 different call centers, Policy Era acts as an advisory and partnership platform which partners with licensed insurers and POSP agents certified and registered under the Insurance Regulatory and Development Authority of India (IRDAI).
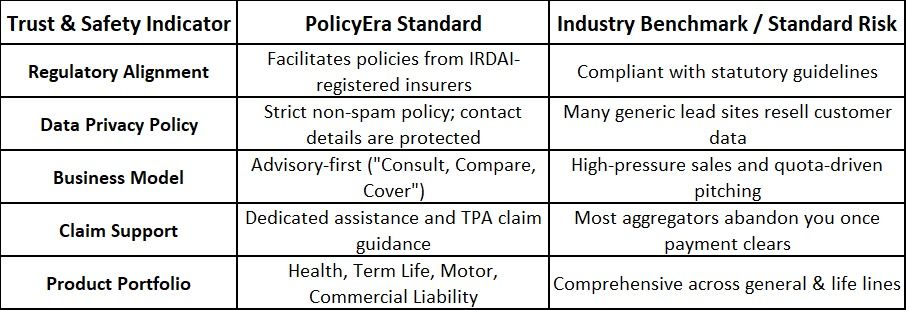
Quick trust summary at a glance
1. Why Are Platforms Like Policy Era Required?
To get an idea about why platforms like Policy Era are required, let's analyze the conventional insurance purchasing experience:
-
The Aggressive Telecaller Problem: You fill your mobile number on an aggregator platform just to compare a rate and receive as many as 15 phone calls in 4 minutes from sales agents of whatever insurance company is willing to offer them the highest commission in that week.
-
The "Fine Print Trap": You purchase a ₹10 Lakh health policy only to realize during hospitalization that there are sub-limits on room rent, co-pay and disease-wise deductibles which reduce your claim amount by 50%.
-
The Disappearing Intermediary: The local agent who has sold you a policy 5 years back either changes his career or stops replying when there's a rejection in your complicated claim and it needs to be contested.
Policy Era was built specifically to address all the above three concerns through human-centric advisory backed up by comparison technologies.
2. How Policy Era Works: "Consult, Compare and Cover" Methodology
While most digital portals operate on a transactional model:
While it is perfect to compare third-party bike insurance through this model, it becomes impractical when dealing with high-end products such as critical illness plans, business liability and term cover plans up to 40 years. Policy Era has defined its user journey in three distinct phases:
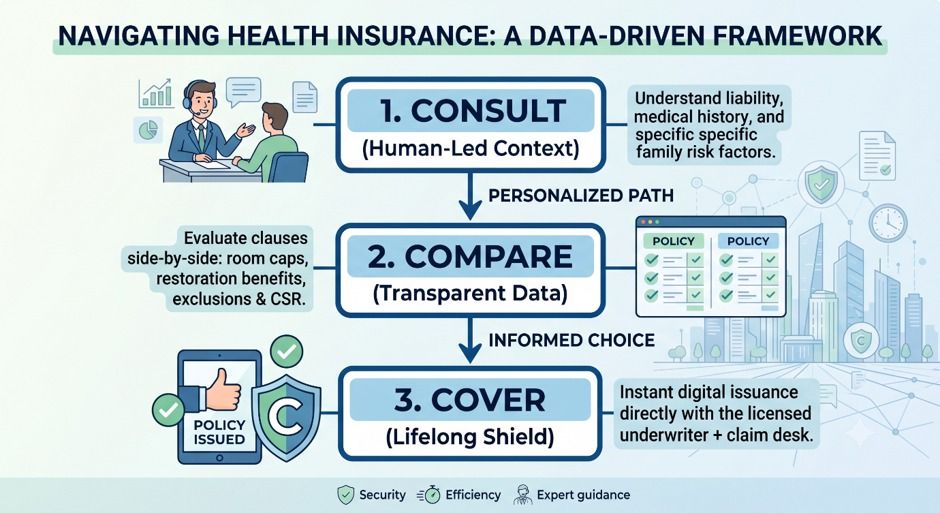
Phase 1: Consult (Diagnosis Before Prescribing)
Instead of forcing you into a standard template, Policy Era first diagnoses your requirements:
• Do you have your elderly parents who have pre-existing conditions such as diabetes and hypertension?
• Is your term cover inflation-adjusted to keep pace with education cost?
• Is your employer's health cover leaving critical illnesses uncovered?
Phase 2: Compare (Understanding the Clauses)
Not only does the platform engine compare plans based on lowest premium but also shows you:
• Incurred Claim Ratios (ICR) and Claim Settlement Ratios (CSR) of insurers.
• Room Rent clauses: Does a policy allow single private AC rooms without making any proportionate deductions?
• Waiting Period: How long is the waiting period of 1 year, 2 years or 3 years for certain illnesses.
Phase 3: Cover (Generation and Archival of the Policy)
Your premium is paid directly to the underwriting insurer. The final policy document, tax exemption certificates (under Section 80D/80C) and cashless health card are generated directly by the licensed insurer.
3. Five Pillars of Policy Era's Trustworthiness
Pillar 1: Non-involvement in Direct Underwriting (No risk for you)
There is a common fear among buyers:
"What if the online platform goes bust in 10 years? My policy will become void."
No. Online portals like Policy Era do not hold the underwriting risk capital of your policy. Your policy contract is an irrevocable legal document between you (policyholder) and the insurance company (such as HDFC ERGO, ICICI Lombard, Star Health, Care Health, Max Life, Tata AIG and other insurers).
If you stop visiting Policy Era after buying your policy, your coverage, policy document, cash value and your right to claim remains fully active and enforceable by law against the insurer and under the IRDAI Ombudsman's jurisdiction.
Pillar 2: POSP Partners and Local Accountability
Policy Era facilitates POSP (Certified Point of Sale Agents). This hybrid approach resolves the problem of technology and lack of local accountability:
• You have the speed and efficiency of modern-day engine.
• You have the personal attention of a professional who knows you by your name and can assist your family in an emergency.
Pillar 3: Absence of Any Hidden Surcharges
The premiums quoted by Policy Era are strictly standardized. As per the insurance regulations in India, an online platform cannot make any premium mark-ups or charge any surcharge on your premium without permission. The rate shown on Policy Era is exactly equal to the statutory premium tariff of the insurer.
Pillar 4: Emphasis on Claim Assistance
The true test of any insurance platform lies not in how fast they deliver your policy but in how they stand behind you during hospital claim investigation and denial. PolicyEra assists you in:
• Initiating cashless authorizations within the network hospitals.
• Preparation of necessary claim files (discharge summaries, indoor case papers, pharmacy invoices with breakups).
• Dispute escalation process through insurer grievance cells and IRDAI Bima Bharosa portal in case of wrongful rejection of your claims by the insurer.
Pillar 5: Data Privacy and Confidentiality
One of the quickest way to lose a customer's trust is by sending them numerous spam calls from the automated system. Policy Era values its client data:
Your personal health disclosures and contact information are not used by the platform for any marketing purpose but for generating accurate quote, facilitating underwriting and delivering your policy.
4. Demystifying the Fine Print: What Policy Era Protects You From?
To illustrate how Policy Era helps you protect yourself from the fine print in an insurance plan purchased without any assistance, take a look at an example below:
Case Study: Danger of "Cheapest Premium" Bias
Assume: Rahul (32 years old) decided to purchase a ₹10 Lakh health plan from an unguided discount website on his own choosing the policy with lowest premium. He has taken gall stone operation worth ₹3,50,000 after 2 years.
Total Hospital Bill: ₹3,50,000
• Room selected: Single Deluxe (₹8,000/day)
• Policy Clause: Room Rent restricted up to 1% of sum assured (₹5,000/day)
• Result: 37.5% limit breach triggering "Proportionate Deduction"
FINAL SETTLEMENT BREAKDOWN:
-
Insurer approved: ₹2,18,750
-
Personal penalty: ₹1,31,250
Net result: Rahul, despite the ₹10 Lakh policy, had to pay
over ₹1.3 Lakh from his personal money because nobody explained him about the room rent cap.
How Policy Era Helps:
The advisor at Policy Era would detect the presence of room rent cap, day care procedure restrictions and modern medical treatment limits before you go ahead with the plan.
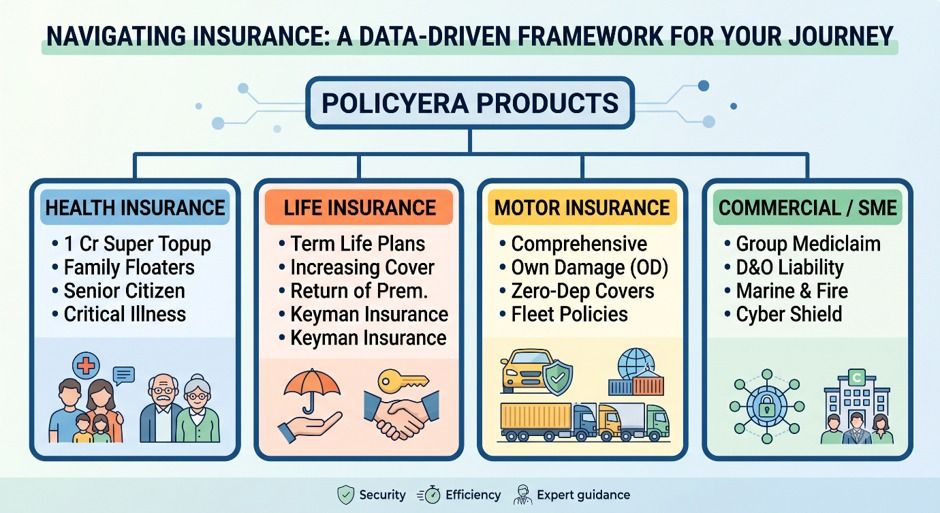
5. What Type of Insurance Policies Can Be Purchased Through Policy Era?
Policy Era provides both personal as well as business risks.
6. How to Verify Any Insurance Intermediary? A Checklist for Buyers
Whether you are verifying Policy Era, a local insurance intermediary or a digital platform, follow the following standard checklist to ensure legitimacy of any insurance intermediary before making any payment:
STEP 1: Verify Payment Destination
The payment gateway should redirect you to the website of the licensed insurance company or authorized regulated escrow partner, not to an individual's personal account.
STEP 2: Verify the IRDAI Registration of the Insurer
Make sure that the insurance company issuing the policy is listed on the IRDAI registration portal (irdai.gov.in).
STEP 3: Verify Real-Time Policy Generation
You must receive the payment receipt and then the 54AA compliant policy document within 5 seconds after successful payment with a unique Policy Number.
STEP 4: Verify via Insurer Customer Portal
Log into the website of the insurance company using your newly acquired Policy Number to view the policy schedule and health cards.
7. Final Verdict: Should You Use Policy Era?
If you want a legitimate, reliable and customer-oriented insurance platform which removes confusion of jargon and misleading sales tactics, then Policy Era is for you.
Through combination of transparent comparison data, professional advisory services and POSP ground-level support, Policy Era makes sure that you buy a real coverage and not a mere policy.
FAQs
1. Is Policy Era an insurance company or an advisory platform?
Policy Era is a consulting platform. It is licensed to provide insurance comparison and advisory services in partnership with various licensed insurance companies.
2. Do I have to pay more if I buy an insurance product through Policy Era?
No. All the tariff rates of premiums of the products are filed by insurance companies with IRDAI which regulate them. Hence, you have to pay the same statutory premium while also getting extra comparison tools and advisory.
3. What if I have a claim on the policy bought through Policy Era?
Your claim will be honored by the underwriting insurance company and will be managed through network hospitals and TPAs. You will receive guidance through Policy Era's team and POSP partners.
4. How does Policy Era safeguard my phone number and personal details?
Policy Era abides by strict data privacy policies. Your phone number and details will be used strictly for underwriting and issuance purposes. They will never be resold to any third-party telemarketers.
5. Is it possible to transfer (port) an existing policy to Policy Era?
Yes. As per the IRDAI regulations, you can port your health insurance policy from your existing intermediary without losing your waiting period credits (in pre-existing diseases/ailments) provided you initiate the process at least 45 days before the expiry of your renewal date.