PolicyEra - Consult Compare Cover

Regulatory & Consumer Protection Rules in Health Insurance: Cashless Everywhere, 5-Year Moratorium & Portability Explained
2026-Oct-22

Consumer reviewing health insurance policy documents and consumer protection rules at home

A consumer reviewing health insurance documents at home, understanding health insurance regulations, cashless treatment, the 5-year moratorium period, policy portability, and consumer protection rights in India.

Health insurance rules in India have changed significantly in recent years, giving policyholders clearer rights around cashless claims, waiting periods, portability and claim contestability. For consumers, the challenge is knowing which rule applies, what timelines must be followed and what benefits actually carry forward when a policy is changed.

This guide explains three high-intent regulatory questions:

  1. How does Cashless Everywhere work in health insurance?

  2. What is the 5-year moratorium period in health insurance?

  3. How can you switch health insurance companies without losing waiting-period and continuity benefits?

The information below is based primarily on the Insurance Regulatory and Development Authority of India (IRDAI) health-insurance framework and related official policyholder guidance. IRDAI's current health-insurance guidance specifies a 1-hour pre-authorisation decision, 3-hour final cashless authorisation and 60 continuous months for the moratorium period.

Quick Answer: Health insurance policyholders can benefit from cashless treatment subject to the insurer's applicable process and policy terms, retain eligible waiting-period credits when porting without a break, and receive stronger protection against non-disclosure/misrepresentation-based contesting after 60 continuous months of coverage, except in cases of established fraud.

How Does Cashless Everywhere Work in Health Insurance?

Cashless Everywhere refers to arrangements that can enable policyholders to seek cashless treatment at hospitals outside an insurer's traditional network, subject to the insurer's process, hospital cooperation, eligibility and policy terms.

It is important not to interpret "Cashless Everywhere" as an unconditional guarantee that every non-network hospital will provide cashless treatment. The hospital must generally agree to participate in the cashless process, and the treatment must be admissible under the policy.

The cashless process also operates within IRDAI's prescribed claims turnaround framework. IRDAI states that the insurer should decide a cashless pre-authorisation request immediately and within one hour, while final authorisation should be provided within three hours of receiving the hospital's discharge-authorisation request.

Cashless Everywhere: 4-Step Checklist

Step 1: Intimate the insurer/TPA

For planned hospitalisation, notify the insurer/TPA in advance according to the applicable cashless process. A commonly used Cashless Everywhere requirement is at least 48 hours before planned admission; for emergencies, notification is generally required as soon as possible and within the applicable insurer's stated timeline. Because operational requirements can differ, always check your policy and insurer/TPA instructions.

Step 2: Obtain hospital consent

Ask the non-network hospital whether it is willing to process the cashless request. The hospital may need to provide a consent letter or complete the prescribed cashless/pre-authorisation documentation.

Step 3: Submit the pre-authorisation information

The hospital and policyholder may need to provide the pre-authorisation form, identification documents, medical records, admission details, proposed treatment and estimated expenses.

Where applicable, the hospital should provide the clinical and billing information required by the insurer/TPA, including the appropriate diagnosis and treatment coding. Do not assume that an "ICD code filing" is a universal consumer requirement; the exact documentation depends on the insurer, TPA and hospital process.

Step 4: Complete discharge sign-off

Once treatment is completed, the hospital submits the final bill and discharge-authorisation request. IRDAI's cashless TAT requires final authorisation within three hours of receipt of the discharge-authorisation request.

Does Cashless Everywhere Mean Any Hospital Will Approve Cashless Treatment?

No. Cashless treatment at a non-network hospital is subject to eligibility, hospital participation, policy coverage and the insurer's applicable process.

A cashless request may not be approved if the hospital does not participate, the treatment is not covered, the claim does not satisfy policy conditions or the required information is not provided.

If cashless treatment is not approved, the policyholder may still be able to submit a reimbursement claim, subject to the terms and conditions of the policy.

What Are the IRDAI Cashless Claim Timelines?
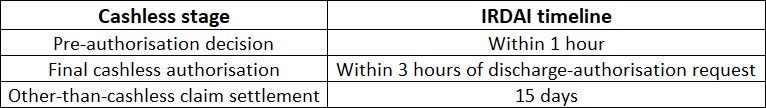
image.png

These are regulatory turnaround requirements; they do not mean every claim is automatically payable. Claim admissibility continues to depend on the policy contract and applicable exclusions.

What Is the 5-Year Moratorium Period in Health Insurance India?

The moratorium period in health insurance is the period after which a health insurance policy and claim generally cannot be contested on grounds of non-disclosure or misrepresentation, except in cases of established fraud.

Under the current IRDAI framework, the moratorium period is 60 continuous months, or five years. IRDAI's 2024 reforms reduced the period from the earlier eight-year framework to five years.

Definition: Moratorium Period in Health Insurance

Moratorium period = 60 continuous months of health-insurance coverage. After completion of the moratorium period, the policy and claim cannot be contested on grounds of non-disclosure or misrepresentation, except for established fraud. Credits accumulated through portability and migration are also counted when calculating the moratorium period.

However, the moratorium rule does not mean that every claim becomes automatically payable after five years. Policy exclusions, coverage limits, sub-limits, co-payments and other contractual conditions can continue to apply.

Can an Insurer Reject a Health Insurance Claim After 5 Years?

An insurer cannot contest a health insurance policy or claim on grounds of non-disclosure or misrepresentation after 60 continuous months, except for established fraud.

But this protection should not be misunderstood as a blanket guarantee of claim approval.

For example, a claim could still be affected by:

• An exclusion specifically mentioned in the policy

• A treatment outside the policy's coverage

• A policy limit or sub-limit

• Co-payment requirements

• Non-medical expenses where applicable

• Established fraud

• Other valid contractual conditions

What Happens When You Increase Your Sum Insured?

The moratorium protection applies to the sum insured of the first policy. If the sum insured is subsequently enhanced, the five-year continuous-coverage requirement applies from the date of enhancement to the enhanced portion.

Example

Suppose your health insurance policy starts with a sum insured of ₹5 lakh.

After three years, you increase it to ₹10 lakh.

Your existing ₹5 lakh portion continues to receive the benefit of your accrued continuity, while the additional ₹5 lakh is subject to the applicable moratorium calculation from the date of enhancement.

Therefore, increasing your sum insured does not necessarily mean the entire policy receives five years of moratorium credit immediately.

Waiting Period vs Moratorium Period: What Is the Difference?
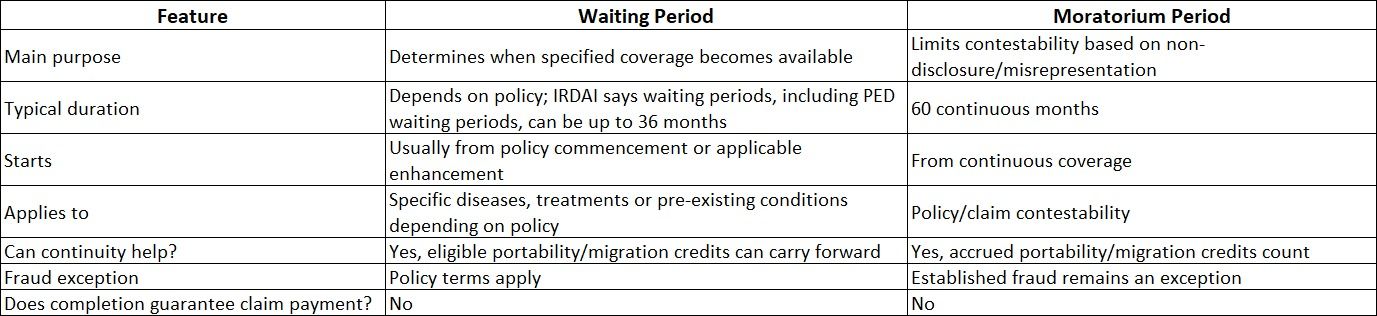
image (1).png

IRDAI currently states that the maximum waiting period under health insurance, including pre-existing disease waiting periods, should not exceed 36 months.

How Can You Switch Health Insurance Companies Without Losing Your Waiting Period?

This process is called health insurance portability.

Portability allows a policyholder to move from one insurer to another while carrying eligible continuity credits, including credits related to pre-existing disease waiting periods and specific waiting periods. IRDAI also states that portability is available for individual, family-floater and group health insurance policies at renewal.

What Benefits Can Carry Forward When You Port Health Insurance?

Depending on the applicable rules and policy structure, portability can protect accrued credits relating to:

• Pre-existing disease waiting periods

• Specific waiting periods

• No Claim Bonus (NCB), where applicable

• Sum insured and accrued bonus to the extent permitted

• Moratorium-period credit

• Other eligible continuity benefits

The exact benefit transferred can depend on the policy, insurer and applicable regulatory framework.

Health Insurance Portability Eligibility Rules

Before switching insurers, remember these important rules:

• Portability is generally exercised at renewal.

• Apply to the new insurer at least 30 days before, but not earlier than 60 days from, the renewal due date, according to IRDAI's current health-insurance guidance.

• You normally port the entire policy along with the covered family members, where applicable.

• Maintain continuous coverage and avoid a break in the policy.

• The acquiring insurer obtains relevant policy and claim information from the existing insurer.

• The existing insurer is required to provide the required data within 72 hours of receiving the request.

• The acquiring insurer should decide and communicate on the portability proposal within five days of receiving the required information from the existing insurer.

Important update: Older health insurance portability articles often mention a 45 day deadline. The current IRDAI health-insurance guidance specifies 30 days before, but not earlier than 60 days from, the renewal due date. For SEO content published today, using the current 30-day rule is safer than repeating the older 45-day rule.

Health Insurance Portability Timeline: From Old Insurer to New Insurer

60–30 Days Before Renewal

Compare policies and start the portability process.

Check:

• Premium

• Sum insured

• Waiting periods

• Room-rent restrictions

• Disease sub-limits

• Co-payment

• Network hospitals

• NCB

• Exclusions

• Restoration benefits

• Claim-service experience

At Least 30 Days Before Renewal

Submit your portability request to the new insurer.

The application should be made within the applicable IRDAI window: not earlier than 60 days and at least 30 days before the renewal due date.

After the Portability Request

The acquiring insurer requests policy and claim information from your existing insurer through the Insurance Information Bureau of India (IIB) process.

The existing insurer has 72 hours to furnish the required information.

Within 5 Days of Receiving the Required Information

The acquiring insurer should decide and communicate the portability proposal within five days of receiving the information from the existing insurer.

Renewal Date

The objective is to move to the new insurer without a break in coverage.

A break in health insurance can jeopardise continuity benefits, so do not cancel the existing policy merely because you have submitted a portability application.

Do You Lose Your No Claim Bonus When You Port Health Insurance?

Not necessarily. Portability is designed to transfer eligible accrued continuity benefits, and IRDAI's health-insurance framework recognises transfer of eligible credits such as No Claim Bonus and waiting-period credits, subject to the applicable rules and policy structure.

However, NCB should not be treated as an unlimited benefit.

For example, if your existing insurer provides a ₹5 lakh base sum insured plus an accumulated NCB, the acquiring insurer may consider the eligible accrued benefit according to portability rules. Any increase beyond the eligible transferred coverage can be subject to fresh underwriting and applicable waiting periods.

Example: Switching Health Insurance Without Losing Waiting-Period Credit

Suppose Ravi has:

• Existing health policy: ₹10 lakh

• Continuous coverage: 4 years

• PED waiting period already served: 4 years

• Existing NCB: ₹2 lakh

• Renewal date: 30 November

Ravi decides to move to another insurer.

He applies within the applicable portability window and maintains continuous coverage.

Because portability is designed to carry forward eligible continuity credits, Ravi should not ordinarily be treated as a completely new customer for the waiting-period credit already earned under his previous coverage.

The exact amount of transferred benefit depends on the applicable policy and portability rules.

If Ravi simultaneously increases his coverage substantially, the additional sum insured can be subject to fresh waiting periods or other applicable conditions.

What Is the Difference Between Portability and Migration?

These terms are frequently confused.

Portability

Portability = moving from one insurer to another insurer.

Example:

Insurer A → Insurer B

The policyholder can transfer eligible continuity credits under the applicable rules.

Migration

Migration = moving from one health insurance product/plan to another with the same insurer.

Example:

Insurer A – Plan X → Insurer A – Plan Y

IRDAI defines migration as a facility allowing policyholders to transfer accrued credits from one health insurance policy to another with the same insurer.

Common Mistakes Policyholders Should Avoid

1. Waiting Until the Last Day to Port

Do not wait until renewal is only a few days away. Start the process within the prescribed portability window.

2. Cancelling the Existing Policy Too Early

Do not create a gap in coverage while waiting for the new insurer's decision.

3. Assuming Portability Means Every New Benefit Is Immediately Available

Portability protects eligible accrued credits. A newly increased sum insured or additional benefit can have separate waiting-period requirements.

4. Assuming Cashless Treatment Is Guaranteed Everywhere

A non-network hospital may need to participate and complete the required process. Always obtain confirmation before admission where possible.

5. Confusing Moratorium With Waiting Period

Completing a waiting period does not mean that the policy has completed its moratorium period.

6. Hiding Medical Information

The five-year moratorium is not permission to conceal medical history. Consumers should always provide accurate and complete information while buying or renewing health insurance.

Key Takeaways for Health Insurance Policyholders

The latest health-insurance framework gives consumers several important protections:

• Cashless claims: IRDAI specifies a 1-hour pre-authorisation TAT and 3-hour final cashless authorisation TAT.

• Cashless Everywhere: Non-network cashless treatment can be available subject to the participating hospital, insurer process and policy conditions.

• Moratorium: The current period is 60 continuous months (5 years).

• Fraud exception: Established fraud remains an exception to the moratorium protection.

• Portability: Eligible waiting-period and continuity credits can move to another insurer.

• Portability window: The current IRDAI guidance says at least 30 days before and not earlier than 60 days from renewal.

• Portability data transfer: Existing insurer — up to 72 hours; acquiring insurer — decision within five days after receiving the required information.

• Waiting periods: IRDAI currently states a maximum of 36 months for waiting periods, including PED waiting periods.

Understanding these rules can help policyholders make better decisions before hospitalisation, before renewal and before switching insurers.

Disclaimer: Insurance rules, insurer processes and policy wording can change. This article is for educational purposes and should not be treated as legal, financial or insurance advice. Always check your policy document, Customer Information Sheet and the latest IRDAI/insurer instructions before making a claim or porting a policy.

Official Regulatory Source

The primary regulatory reference for this article is IRDAI's Master Circular on Health Insurance Business dated 29 May 2024, along with IRDAI's current health-insurance policyholder guidance.

FAQs

1. How does Cashless Everywhere work in health insurance?

Cashless Everywhere can enable eligible policyholders to seek cashless treatment at participating non-network hospitals, subject to hospital consent, insurer/TPA procedures, policy coverage and claim admissibility. IRDAI's cashless framework requires pre-authorisation decisions within one hour and final cashless authorisation within three hours of the discharge-authorisation request.

2. Can I get cashless treatment at a non-network hospital?

Potentially, yes. Cashless treatment at a non-network hospital depends on whether the hospital agrees to participate in the applicable Cashless Everywhere process, whether the insurer supports the facility and whether the treatment satisfies the policy terms.

3. What is the moratorium period in health insurance India?

The current health-insurance moratorium period is 60 continuous months, or five years. After this period, a policy and claim generally cannot be contested on grounds of non-disclosure or misrepresentation, except for established fraud.

4. Can an insurer reject a claim after five years?

A claim cannot be contested on grounds of non-disclosure or misrepresentation after completion of the 60-month moratorium period, except for established fraud. However, other valid policy conditions, exclusions, limits and co-payments can still apply.

5. How do I switch health insurance companies without losing waiting-period benefits?

Use the portability process at renewal, apply within the prescribed 60-to-30-day window, provide the required information and maintain continuous coverage. Eligible waiting-period and other continuity credits can then be transferred under the applicable rules.

6. Does health insurance portability carry forward NCB?

Eligible NCB and other continuity credits may be transferred under portability, subject to the applicable regulatory framework and policy terms.

7. Is the old 45-day portability rule still applicable?

The current IRDAI health-insurance guidance specifies that a portability application should be made at least 30 days before, but not earlier than 60 days from, the renewal due date. The 45-day requirement appears in older portability guidance and should not be presented as the current standard without qualification.

8. Does portability reset my moratorium period?

No. Eligible accrued credits from portability and migration are counted when calculating the moratorium period.

BLOG

Latest Blogs

Stay up-to-date with the world of insurance.

Vehicle Insurance

All you need to know about TP and comprehensive insurance

Insurance is essential to financial planning and can protect you and your assets from unexpected events, such as accidents or natural disasters.

Vehicle Insurance

Understanding Car Insurance: Coverage, Terms & Benefits

Choosing the right auto insurance plan can take a lot of time and effort, as there are several car insurance coverage types.

Health Insurance

Reduce Your Tax Liability with Health Insurance: An Overview of Section 80D of the Income Tax Act

Investing in medical coverage is a wise decision that can help protect you from the financial burden of unexpected medical expenses.

Health Insurance

Health Insurance: Essential Coverage for Every Stage of Life

Health insurance is an essential part of a comprehensive financial plan.

Health Insurance

The Importance of Health Insurance for Senior Citizens in India

Health insurance for senior citizens in India is an important consideration, as medical expenses are high in the country.

Vehicle Insurance

Is Driving a Vehicle without Insurance Illegal in India?

You could break the law by not carrying the appropriate insurance while driving on public roads in India. You should know that third-party liability insurance is legally required for everyone who operates a vehicle on public roads in India.

Term life Insurance

Protect Your Family and Save on Taxes: The Advantages of Life Insurance

Life insurance is a financial product that provides financial protection to your loved ones in the event of your untimely demise. In addition, it ensures that your family is financially secure and offers several tax benefits.

Term life Insurance

Don't Leave Your Family's Financial Future to Chance: The Importance of Life Insurance

Life insurance is a financial product that provides financial protection to individuals and their families in the event of the policyholder's death.

Professional Indemnity Insurance

All about Professional Indemnity for Doctors

A legal liability is like an iron trap, a single step in it might lose one’s legs. However, professional indemnity can safeguard you from the iron trap of legal liability.

Professional Indemnity Insurance

Crucial Role of Indemnity Insurance for Doctors

In this unpredictable and huge ocean of healthcare, a doctor controls the helm, balancing the art of healing others with continuous turbulence. Yet, some very skilled captains come in contact with storms that are legal complexities, which can be a reason to compromise with the professional standards and their career.

Professional Indemnity Insurance

All about Hospital Indemnity

Hospital indemnity insurance is insurance designed to cover specific costs incurred during hospitalization. This blog highlights the importance of hospital indemnity insurance for non-doctor healthcare professionals in India.

Professional Indemnity Insurance

Medico-Legal Services by Policy Era

Medico-legal services encompass a range of legal and insurance solutions tailored to protect doctors, hospitals, and other healthcare providers against potential legal and financial liabilities arising from their professional activities.

Professional Indemnity Insurance

All About Medico-Legal Challenges

Medico-legal cases in hospitals refer to incidents where medical and legal aspects overlap. These cases arise when medical professionals encounter situations with potential legal consequences. The main aim of managing MLCs is to balance patient care with legal obligations while minimizing risks to the hospital and healthcare staff.

Professional Indemnity Insurance

Legal Cases Involving Doctors

The rising number of cases against doctors in India is a pressing concern that requires attention from both the medical and legal communities. While patient rights and medical accountability are crucial, it is equally important to protect doctors from undue legal harassment.

Professional Indemnity Insurance

Budget 2025 & Healthcare

The Union Budget 2025 has been a highly anticipated financial blueprint, especially for the healthcare sector, which continues to evolve with rising patient demands, medical advancements, and the push toward universal health coverage. This year’s budget directly impacts doctors, hospitals, and healthcare professionals by shaping policies around infrastructure, accessibility, and affordability of medical services.

Professional Indemnity Insurance

How Doctors Can Prevent Negligence Claims

Medical negligence lawsuits are skyrocketing across the globe, putting doctors and healthcare professionals in an increasingly vulnerable position. With patients becoming more informed about their rights and legal battles playing out online for the world to see the risks have never been higher. A single lawsuit can shatter a doctor’s career, drain finances, and tarnish their hard-earned reputation.

Professional Indemnity Insurance

Doctors Beware: Essential Risk Management Strategies

For doctors, the stakes are high: a single misstep can lead to lawsuits, career setbacks, or even violence from disgruntled patients. In this challenging landscape, merely reacting to problems as they arise is no longer an option. The need of the hour is a proactive risk management strategy that protects doctors, upholds medical ethics, and ensures optimal patient care.

Professional Indemnity Insurance

Strategic Action Plan for Doctors Facing Negligence Allegations

This blog uncovers the essential steps every medical professional must take when facing negligence allegations

Top 7 People Who Were the Only Survivors of Plane Crashes

This blog chronicles the extraordinary real-life stories of individuals who survived plane crashes completely alone, including the recent Air India tragedy.

Professional Indemnity Insurance

Why Medical Indemnity Insurance is Essential!

Medical indemnity insurance, also known as medical malpractice insurance, is a specialized policy that provides coverage to healthcare professionals against legal claims arising from alleged negligence, errors, or omissions in treatment.

Fire & Burglary Insurance

The Ultimate Guide to Fire Insurance for Clinics & Hospitals

Understanding Fire Insurance: Fire insurance for clinics and hospitals is a policy that provides financial protection against losses and damages caused by fire-related incidents.

Vehicle Insurance

Motor Insurance in India, More Than Just a Legal Requirement

This blog explains why motor insurance in India is more than just a legal formality. It highlights how a well-chosen car or two-wheeler policy protects against accidents, theft, and third-party liabilities. With insights on customisation, online convenience, and long-term plans, it guides readers to make smarter insurance choices. A practical read for every responsible vehicle owner.

Critical Illness Insurance

Critical Illness Insurance, Your Financial Backup When Life Takes A Turn

This blog highlights the importance of critical illness insurance as a financial safety net during life-altering health crises. Through real-life inspired examples, it explains how policies offer support for cancer, heart disease, and severe injuries. It outlines the benefits of lump sum payouts, income replacement, and recovery support. A must-read guide for anyone planning long-term financial protection.

Personal Accident Insurance

Accident Insurance, Because Accidents Don’t Come With a Warning

This blog explores why a personal accident insurance policy is essential in today’s unpredictable world. It highlights how the right accident cover provides income during disability, pays for hospitalisation, and supports families after accidental death.

Top 7 Mistakes People Make While Buying Insurance in India (And How Policy Era Helps You Avoid Them)

This blog reveals the top 7 mistakes people often make while buying insurance in India and how Policy Era helps avoid them. From underinsurance to agent-driven decisions, it highlights real issues with practical solutions.

Term life Insurance

Why Life Insurance Is a Must-Have for Every Earning Member

This blog explains why every earning member must secure their family’s future against debt, lifestyle disruption, and uncertainty. It covers types of life insurance and when to buy. With Policy Era’s expert guidance, protection becomes simple, smart, and personal.

Health Insurance

How Health Insurance Protects You from Medical Emergencies and Rising Hospital Bills

This blog explores how health insurance protects individuals and families from rising hospital costs and unexpected medical emergencies. It highlights real treatment expenses in India and explains the value of private medical insurance.

Why Insurance Is the Smartest Way to Prepare for Life’s Unexpected Events

This blog explores why insurance is the smartest way to prepare for unexpected events like illness, accidents, or loss. From life and health to home and travel, each policy plays a critical role in protecting your future. With Policy Era’s expert guidance, staying financially secure becomes simple, personalised, and stress-free.

Term life Insurance

Term Insurance vs. Whole Life Insurance – What’s Best for You?

This blog breaks down the key differences in coverage, premium, and long-term value to help you choose smartly. Whether you want affordable protection or lifelong security with savings, we’ve got you covered. With Policy Era’s personalised advice, finding the right policy becomes easy and stress-free.

Travel Insurance

Travel Insurance, Your Best Friend on International Trips

This blog explains why travel insurance is an essential companion for international trips. It covers how the right policy protects against medical emergencies, baggage loss, and trip cancellations.

Home Insurance

Home Insurance: Protect Your Property from Fire, Theft, and Natural Calamities

This blog explains the rising need for home insurance in India, especially in disaster-prone and urban areas. From policy types to common add-ons, it’s a complete guide to securing your property. With Policy Era’s expert help, protecting your home is simple, affordable, and stress-free.

Term life Insurance

8 Life Events That Mean You Should Consult Policy Era Now

This blog highlights eight major life events that demand immediate review of your insurance and legal plans. From marriage to retirement, each phase brings new risks and responsibilities.

Five Insurance Myths That Are Costing You Money

This blog exposes five common insurance myths that lead to financial mistakes. From believing youth equals immunity to trusting company cover blindly, these misconceptions can cost you heavily.

Women & Insurance: Plans That Fit Different Life Stages

This blog explores insurance strategies tailored for women at every stage of life. From maternity cover for young women to critical illness protection and retirement-focused plans, it highlights why customised coverage is essential.

Health Insurance

Understanding Pre-Existing Diseases in Health Insurance

This blog explains what pre-existing diseases mean in health insurance, why declaring them correctly is essential, and how waiting periods affect coverage.

Term life Insurance

NRI Guide to Buying Term Insurance in India

This blog serves as a comprehensive guide for NRIs looking to buy term insurance in India. It explains eligibility, policies that offer worldwide claim support, and the medical check-up process abroad.

Cashless vs Reimbursement Claims: Which One Is Better?

Cashless and reimbursement claims are two popular ways to settle health insurance bills, but which is better? This guide explains how each process works, its pros and cons, and when to choose one over the other.

Term life Insurance

What Is Human Life Value (HLV) in Insurance and Why It Matters?

This article explains what HLV is, how it is calculated, and why it matters for long-term financial planning. We explore its role in deciding the right sum assured, its link to dependents and liabilities, and the ideal HLV ratio for different life stages.

GST Reforms Explained: What Insurance Buyers Must Know

The 2025 GST reforms have removed GST on individual life and health insurance premiums, making coverage more affordable for millions of Indians. This blog explains the changes, their impact on premiums, and how they affect financial planning. With expert insights and future outlook, it highlights why now is the best time to strengthen your insurance portfolio.

Cyber Insurance

Cyber Insurance for Financial Institutions

Cyber threats are rising fast in the financial sector, making banks and NBFCs prime targets for ransomware, fraud, and data breaches. This blog explains how cyber insurance safeguards institutions against financial, legal, and reputational risks. It covers benefits, compliance aspects, and the role of Policy Era in providing tailored protection.

Insurance in Indian Family Structures: Joint vs Individual Policies

This blog explains the difference between joint family floater insurance policies and individual cover, highlighting pros, cons, and claim examples.

Health Insurance

How to Choose the Right Sum Insured for Your Family’s Health Plan

Choosing the right sum insured is crucial to ensure your family’s health plan truly protects against medical emergencies. This blog explains how to factor in age, medical history, city-specific costs, inflation, and floater vs individual plans.

Health Insurance

What is a Floater Policy & Who Should Choose It?

This blog explains what a floater health insurance policy is, how it works, and who should consider it. It covers advantages like affordability and convenience for nuclear families, along with limitations such as coverage sharing.

Critical Illness Insurance

Why Critical Illness Insurance is a Must in India

Critical illness insurance in India provides financial protection against expensive lifestyle-related diseases such as cancer, heart attack, and kidney failure. Unlike standard mediclaim policies, it offers a lump-sum payout upon diagnosis of 30+ major illnesses.

Personal Accident Insurance

Top 5 Reasons: Why You Need Accidental Insurance Today?

Accidental insurance provides crucial financial protection in the event of sudden injuries, disability, or unforeseen emergencies caused by accidents. It helps cover medical expenses, loss of income, and long-term recovery needs that standard health insurance may not fully support.

Understanding Policy Riders and Endorsements

Understanding policy riders and endorsements is essential for anyone looking to customise their insurance coverage. These add-ons help enhance protection in life, health, and property policies without having to purchase entirely new plans

Health Insurance

Health Insurance Myths Debunked!

This blog clears the confusion surrounding health insurance by breaking down key concepts, addressing common myths, and highlighting why understanding your policy matters.

Term life Insurance

The Benefits of Whole Life Insurance

Health Insurance

When Does Health Insurance Cover Dental Treatment?

Understanding how dental benefits work, what procedures are covered, and the types of plans that offer such support helps individuals make informed healthcare decisions.

Term life Insurance

Top Myths About Buying Online Life Insurance

This blog breaks down the most common myths and reveals why digital buying is safer, simpler, and more affordable.

Vehicle Insurance

Sikkim Hosts a Landmark Supercar Rally in the Heart of the Himalayas

This prestigious supercar rally, featuring high end brands such as Mercedes, Porsche, Lamborghini and BMW, is insured by Policy Era Insurance Broking Firm. The event showcases the scale, luxury and thrill of an ongoing high performance automotive experience set against the Himalayan landscape.

Health Insurance

Factors to Consider When Choosing a Health Insurance

This blog explains the key factors every individual should consider before choosing a policy.

Office Package Policy

Office Package Insurance for Business Assets

Office Package Insurance protects business assets from fire, theft, accidental damage and liability, ensuring continuity and financial stability.

Investment Plans

Gold Rate in India at Record Highs: Buy or Wait?

Gold prices hit record highs in India. Buy or wait? Learn how to balance gold investment with insurance for smarter financial protection.

Baba Vanga’s 2026 Prediction: What Would Humanity’s First Alien Encounter Mean for Insurance and Risk Planning?

Baba Vanga’s 2026 alien prediction sparks a serious question—how prepared is the insurance industry for unprecedented global risks?

Baramati Plane Crash: Ajit Pawar Death Raises Safety Concerns

A tragic plane crash in Baramati claiming the life of Maharashtra Deputy CM Ajit Pawar highlights how suddenly life can change—and why financial and insurance preparedness is essential for every family.

Health Insurance

Choosing the Right Sum Insured in 2026 Using Indian Medical Inflation Data

Understand how Indian medical inflation impacts health insurance in 2026 and learn how to choose the right sum insured to stay financially protected.

Cyber Insurance

Cyber Insurance in India for Small Businesses | PolicyEra

Cyber threats are rising in India. Learn why cyber insurance is vital for small businesses and how PolicyEra helps you choose the right coverage.

Health Insurance

Are Hospitals Inflating Bills? What Insurance Policyholders Need to Know

This blog examines concerns around rising hospital bills and their impact on health insurance policyholders in India. It explains common billing practices, areas of dispute, and how insurers evaluate treatment costs. Readers gain clarity on their rights, responsibilities, and the importance of transparency. The blog helps policyholders make informed decisions during hospitalisation and claims.

Health Insurance

How Claims Portal Reforms Could Lead to Fairer Treatment Costs and Better Insurance Access

This blog examines concerns around rising hospital bills and their impact on health insurance policyholders in India. It explains common billing practices, areas of dispute, and how insurers evaluate treatment costs. Readers gain clarity on their rights, responsibilities, and the importance of transparency. The blog helps policyholders make informed decisions during hospitalisation and claims.

Health Insurance

Why Buying Insurance Through a Broker Is Safer

Discover why buying insurance through a broker like Policy Era is safer than online. Get expert advice, better coverage & claim support.

Investment Plans

One Advisor for All Insurance Policies | Policy Era

Learn why buying all insurance policies from one advisor saves money, avoids coverage gaps, and simplifies claims. Get expert help with PolicyEra.com

Health Insurance

Right Sum Insured in 2026 | Indian Medical Inflation Guide

Learn how to choose the right health insurance sum insured in 2026 using Indian medical inflation trends, healthcare costs, and coverage needs.

Health Insurance

2026 Health Insurance Changes for Senior Citizens India

Explore 2026 health insurance changes for senior citizens in India, including renewability, waiting periods, premiums, claims and coverage.

Health Insurance

How Right Insurance Makes a Difference in Financial Life

Discover how the right insurance provides financial stability, claim readiness, and long-term protection for families, professionals, and businesses.

Shop Owner Insurance

Medical Shop Insurance for Stock Fire Theft Cover

Protect your medical shop from fire theft stock loss and disasters Compare insurance plans with PolicyEra and choose the right cover.

Investment Plans

Investment Plan Insurance vs Mutual Funds in India

Compare investment plan insurance vs mutual funds in India. Learn key differences, benefits, and choose the right wealth creation option with PolicyEra.

Health Insurance

Why Cheap Insurance Costs More Later | PolicyEra

Cheap insurance may save money today but cost lakhs later. Learn the hidden risks, coverage gaps, and choose smarter insurance with PolicyEra.

Health Insurance

Why Cheap Insurance Costs More Later | Policy Era

Cheap insurance may save money today but cost lakhs later. Learn the hidden risks and choose better coverage with Policy Era.

Shop Owner Insurance

Medical Shop Insurance for Pharmacy Owners | PolicyEra

Protect your pharmacy with medical shop insurance. Compare plans, get expert advice, and hassle-free claim support with Policy Era.

Health Insurance

Rising Healthcare Costs in India | Insurance Planning

Healthcare costs in India are rising. Learn why smart insurance planning protects your savings and ensures long-term financial security.

Super Top up

Super Top Up Health Insurance Made Clear

Facing bills that climb quicker than paychecks - that’s life now across India. Hospital stays often hit five to ten lakhs, sometimes way beyond, particularly in big-city clinics. Sure, holding an insurance plan helps, yet gaps remain when numbers soar too high. Here enters the idea of a Super Top-Up health plan. Let’s break it down in simple, non-technical language.

Super Top up

Super Top Up Insurance Lowers Growing Healthcare Expenses in India

Investment Plans

Tax Planning with Investment Insurance and Section 80C

Health Insurance

What Increased Investment in Medical Infrastructure Means for Patients and Insurers in Uttar Pradesh

Uttar Pradesh is witnessing significant investment in medical infrastructure across public and private sectors. This blog analyses how improved facilities affect patient access, treatment quality, and insurance utilisation. It also explains the implications for insurers managing higher volumes and costs. Readers gain insight into how infrastructure growth reshapes healthcare economics.

Health Insurance

What Type of Insurance Coverage Do Indians Prefer Now?

This blog examines current insurance preferences among Indian consumers and how protection priorities are evolving. It highlights growing demand for life, health, and comprehensive coverage driven by rising financial and medical risks. The piece explains key trends shaping consumer behaviour and coverage choices. It also underscores the importance of informed advisory support in translating preference into effective protection.

Health Insurance

What’s Your Biggest Financial Fear?

This blog examines the most common financial fears faced by individuals and families in 2026, from income loss to rising medical costs and inflation. It explains how life insurance and health insurance address these risks in a structured and practical way. The article highlights the dangers of relying on a single financial product and the importance of balanced planning. It underscores how informed insurance decisions build long term financial confidence and security.

Health Insurance

Why Cashless Insurance Claims Are Under Pressure in India Now

Cashless health insurance claims are facing increasing scrutiny due to rising costs and regulatory changes. This blog explores the reasons behind delays, rejections, and stricter approvals. It explains how hospital practices, insurer controls, and claim ratios influence the cashless system. Readers learn how to navigate claims more effectively in the current environment.

Health Insurance

Why Insurance Claims Get Rejected in India and What You Can Do

Learn why insurance claims get rejected in India and discover practical tips to avoid claim denials through accurate disclosures, timely filing, proper documentation, and the right coverage.

Health Insurance

Why Insurance Matters in 2026 Trends, Insights, and What It Means for You

This blog explains why insurance has become a core pillar of financial security in 2026 amid rising health, economic, and lifestyle risks. It explores key insurance trends and sector growth while highlighting the importance of informed planning for families and businesses. The piece aligns insurance decisions with long-term life goals rather than short-term cost considerations. It also reflects how advisory-driven platforms like Policy Era help individuals make transparent, compliant, and well-informed insurance choices.

Investment Plans

Young Professionals Building Wealth with Investment Insurance

Health Insurance

Your Insurance Questions Answered Top Queries in 2026

This blog answers the most common insurance questions people are asking in 2026 as risks and coverage needs continue to evolve. It explains how much insurance is enough, whether corporate cover is sufficient, and what policies suit professionals and freelancers. The article clarifies term insurance, riders, and claim-related concerns with practical insight. It helps readers make informed insurance decisions with confidence and clarity.

Cyber Insurance

Cyber Insurance for Small Businesses in India: Financial Protection from Ransomware & Data Theft

Director & Officer's Liability Insurance

Directors and Officers Insurance for Startups: Coverage, Cost, and When Indian Startups Need It

Health Insurance

Health Insurance Claim Settlement Ratio (CSR): Top Insurers Compared

Term life Insurance

How to Choose the Best Life Insurance Policy for Family

Health Insurance

Is It Covered? Health Insurance Coverage in India: Robotic Surgery, Non-Medical Expenses & Mental Health

Is Policy Era a Legitimate Insurance Platform? An Honest and Uncensored Analysis Before You Purchase

Investment Plans

Investment Insurance: Secure Your Future Today

IRDAI Distribution Reforms 2026: What Do They Mean for Insurance Buyers?

Vehicle Insurance

Motor & EV Insurance in India: Zero Depreciation, EV Battery Cover & NCB Transfer Guide

Should I Still Use Insurance Brokers With New Commission Rules?

Term life Insurance

Term Life Insurance Benefits for Gen Z: Why Buying Early Is the Smartest Financial Decision

Regulatory & Consumer Protection Rules in Health Insurance: Cashless Everywhere, 5-Year Moratorium & Portability Explained