Term life Insurance
Term Life Insurance Benefits for Gen Z: Why Buying Early Is the Smartest Financial Decision
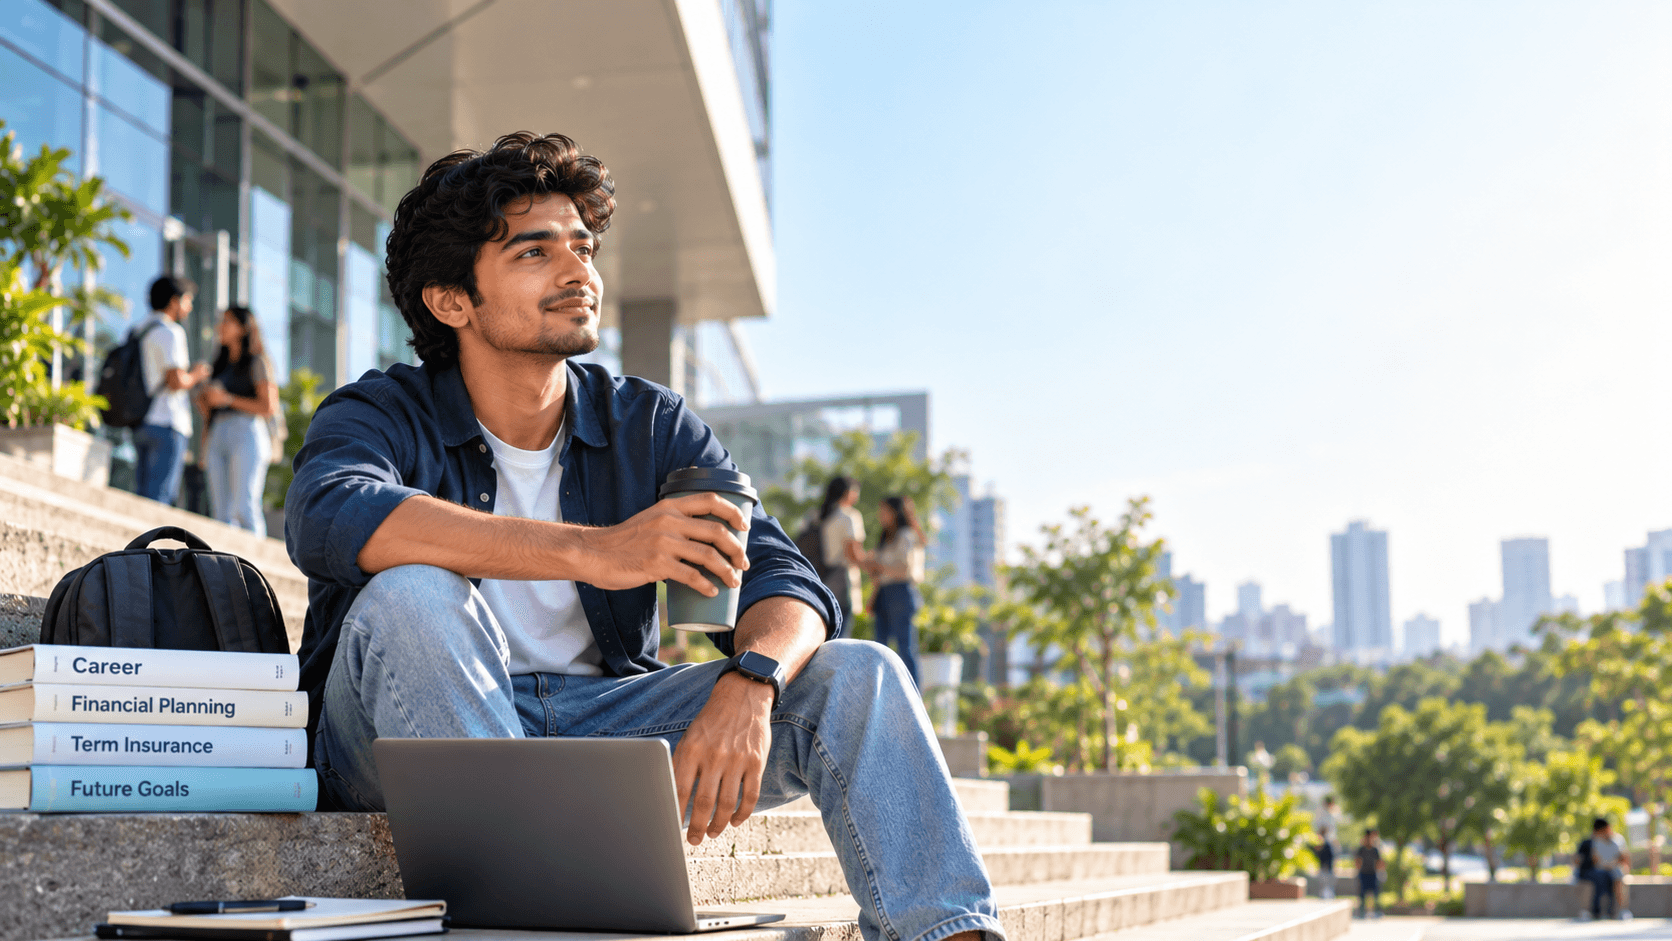
A young man sits on college campus steps with a laptop, coffee cup, and a stack of books labeled Career, Financial Planning, Term Insurance, and Future Goals, visualizing early life planning for Gen Z.
If you're part of Gen Z, chances are you're focused on building your career, enjoying financial independence, or planning your next big milestone. Life insurance probably isn't something that comes to mind every day. After all, many young adults believe it's something to think about after getting married, buying a house, or starting a family.
The reality, however, is quite different.
One of the smartest financial decisions you can make in your 20s is investing in Term Life Insurance. Buying a policy while you're young and healthy allows you to enjoy lower premiums, secure higher coverage, and protect your future financial goals long before major responsibilities arrive.
Whether you've just landed your first job, started your own business, or begun planning your financial future, understanding the Term Life Insurance benefits for Gen Z can help you make a decision that pays off for decades.
Let's explore why purchasing Term Life Insurance early could be one of the best investments in your financial future.
What Is Term Life Insurance?
Simply put, Term Life Insurance is a pure protection plan designed to provide financial support to your loved ones if something unfortunate happens to you during the policy term. Unlike many traditional life insurance plans, it focuses entirely on protection rather than combining insurance with investment.
If the policyholder passes away during the policy period, the nominee receives the agreed Life Cover, helping them manage financial responsibilities without additional stress.
One of the biggest reasons Term Life Insurance has become popular among Young Professionals is its affordability. A healthy individual in their 20s can often secure a substantial Sum Assured, such as ₹1 Crore Term Life Insurance, by paying a relatively low premium compared to someone who purchases the same policy later in life.
Why Should Gen Z Buy Term Life Insurance?
Many people assume they have plenty of time before they need life insurance. Since most Gen Z individuals are just beginning their careers, it's common to postpone buying a policy.
However, waiting could end up costing much more in the long run.
Here are some reasons why buying Term Life Insurance early makes financial sense.
1. Lower Premiums for Life
Insurance companies calculate premiums based on several factors, including age and health. The younger you are, the lower the risk from the insurer's perspective.
That means buying Term Life Insurance in your 20s allows you to lock in an Affordable Premium for the entire policy duration. Instead of paying significantly more later, you can enjoy the same coverage at a much lower cost.
This is one of the biggest reasons financial experts recommend buying Term Life Insurance soon after receiving your First Salary Financial Planning begins.
2. Better Health Means Better Coverage
Most Gen Z individuals are generally healthier than older applicants. Because of this, insurers are more likely to offer comprehensive coverage without adding extra premium charges due to medical conditions.
Purchasing a policy while you're healthy also reduces the chances of facing complicated medical underwriting later in life.
In simple words, buying early gives you access to better protection at a lower cost.
3. Long-Term Financial Security
Financial responsibilities don't appear overnight—they grow with time.
Today, you may be focused on your career, but in the future you may have parents to support, a spouse, children, or even a home loan to repay.
Having Term Life Insurance in place ensures that your loved ones receive the financial support they need if you're no longer around to provide for them.
This is where Financial Security becomes more than just a goal—it becomes a promise to your family.
4. Financial Protection for Parents
Many young professionals contribute to household expenses or support their parents financially. Even if you're currently unmarried, your income might already be an important part of your family's monthly budget.
In such situations, Financial Protection through Term Life Insurance can make a significant difference.
If an unfortunate event occurs, the insurance payout can help your parents manage everyday expenses, outstanding debts, and other financial commitments without additional hardship.
Top Benefits of Term Life Insurance for Gen Z
Buying Term Life Insurance isn't just about preparing for unexpected situations. It's also about making smart financial decisions early in life.
Here are some of the biggest advantages.
Affordable Life Cover
One of the most attractive features of Term Life Insurance is that it provides a large Life Cover without requiring a huge investment.
For a relatively small annual premium, young adults can secure a ₹1 Crore Term Life Insurance policy that protects their family's future for several decades.
This makes it one of the most cost-effective financial products available today.
Income Replacement
As your career progresses, your income becomes one of your greatest financial assets.
If something unexpected happens, your family may suddenly lose the income they depend on. A Term Life Insurance policy provides Income Replacement, helping your loved ones continue paying household expenses, education costs, EMIs, and other financial obligations.
Instead of worrying about immediate financial challenges, your family receives the support they need to move forward with confidence.
Coverage for Future Liabilities
Most Gen Z professionals have ambitious financial goals.
You may plan to buy a home, start a business, pursue higher education, or take a personal loan in the coming years.
Having Term Life Insurance means these future liabilities won't become an unexpected burden on your family.
The policy provides financial assistance that can help settle outstanding obligations while protecting your loved ones from financial uncertainty.
Tax Benefits
Besides offering financial protection, Term Life Insurance also provides valuable Tax Benefits.
Premiums paid toward eligible policies may qualify for deductions under Section 80C, while the death benefit received by the nominee is generally exempt under Section 10(10D), subject to the prevailing provisions of the Income Tax Act.
This means you're not only securing your family's future but also making your Long-Term Financial Planning more tax-efficient.
Peace of Mind
Money alone can't replace peace of mind.
Knowing that your family will have financial support if life takes an unexpected turn allows you to focus on building your career, achieving your dreams, and planning your future with confidence. For many Young Professionals, that's one of the greatest advantages of buying Term Life Insurance early.
How Much Term Life Insurance Does Gen Z Need?
Buying Term Life Insurance is only the first step. Choosing the right amount of coverage is just as important. A policy with insufficient coverage may not provide the financial protection your loved ones would actually need.
A common rule followed by financial experts is to opt for a Life Cover that is around 10 to 20 times your annual income. However, your ideal Sum Assured should depend on your personal financial goals and responsibilities rather than a fixed formula.
Before deciding on the coverage amount, consider factors such as:
• Your current annual income
• Any outstanding loans or future liabilities
• Financial support required for your parents or dependents
• Inflation and rising living expenses
• Long-term financial goals
• Future education expenses for children
• Lifestyle and family responsibilities you expect in the coming years
For many Young Professionals, choosing a ₹1 Crore Term Life Insurance policy is an excellent starting point. It provides meaningful protection while keeping the premium affordable, especially when purchased at a younger age.
Common Mistakes Gen Z Should Avoid
While buying Term Life Insurance is a smart move, making the wrong decisions during the purchase process can reduce its overall value. Here are some common mistakes that many first-time buyers make.
Waiting Too Long
One of the biggest misconceptions is that life insurance can wait until marriage or parenthood. The truth is that every year you delay purchasing Term Life Insurance, your premium is likely to increase. Buying early helps you secure an Affordable Premium and long-term savings
Choosing Low Coverage
Many people select the lowest possible Life Cover simply to reduce their premium.
Although this may seem economical today, inadequate coverage may not be enough to protect your family's future financial needs. Always calculate your expected responsibilities before deciding on the Sum Assured.
Ignoring Insurance Riders
Basic coverage is important, but additional Insurance Riders can make your policy even stronger. Some of the most valuable riders include:
• Accidental Death Benefit Rider
• Waiver of Premium Rider
These riders provide additional financial support during unexpected situations and often come at a reasonable extra cost.
Hiding Medical Information
Some applicants avoid disclosing existing health conditions in an attempt to secure lower premiums.
This is never advisable.
Providing inaccurate or incomplete medical information may create complications during claim settlement. Being transparent ensures that your family receives the policy benefits without unnecessary difficulties.
Buying Only Based on Price
The cheapest plan isn't always the best choice.
Instead of comparing only premiums, also evaluate important factors like:
• Claim Settlement Ratio
• Financial strength of the insurer
• Customer support quality
• Available Insurance Riders
• Policy flexibility
• Overall benefits
A slightly higher premium may provide significantly better protection and service in the long run.
How to Choose the Best Term Life Insurance Plan
With many insurers offering different plans, choosing the right Term Life Insurance policy can feel overwhelming. Fortunately, focusing on a few important factors can make the decision much easier.
Claim Settlement Ratio
The Claim Settlement Ratio indicates how consistently an insurer has settled claims in the past.
Although it shouldn't be the only deciding factor, a strong claim settlement record can provide additional confidence when selecting an insurer.
Adequate Sum Assured
Don't choose coverage based only on your current income.
Think about your future responsibilities, including family expenses, loans, children's education, and long-term financial goals. Selecting an appropriate Sum Assured today can help protect your family for many years.
Affordable Premium
The best insurance policy is one you can comfortably continue paying throughout the policy term. Look for an Affordable Premium that fits your monthly budget while still providing sufficient Life Cover.
Useful Insurance Riders
Different people have different financial needs.
If you're concerned about health-related expenses or accidental risks, adding suitable Insurance Riders can strengthen your overall protection without dramatically increasing your premium.
Customer Support
Insurance is not just about buying a policy—it's also about receiving support when it matters most.
Choose an insurer known for responsive customer service, smooth documentation, and reliable claim assistance.
Why Buying Through an Insurance Broker Can Be Beneficial
With numerous insurance companies offering similar products, comparing plans on your own can become confusing.
Working with an experienced Insurance Broker simplifies the process and helps you make an informed decision.
An Insurance Broker can assist you by:
• Comparing policies from multiple insurers
• Explaining policy features in simple language
• Recommending suitable Life Cover
• Helping you select the right Insurance Riders
• Assisting with documentation
• Providing support during claim settlement
Instead of spending hours researching individual plans, you receive expert guidance tailored to your financial goals.
Final Thoughts
Building wealth is important, but protecting it is equally essential.
For Gen Z, buying Term Life Insurance isn't about expecting something bad to happen. It's about making a responsible financial decision while you're young enough to enjoy the biggest advantages.
Purchasing Term Life Insurance early allows you to secure an Affordable Premium, obtain a higher Life Cover, strengthen your Financial Security, and provide lasting Financial Protection for the people who matter most.
Whether you're a salaried employee, entrepreneur, freelancer, or someone who has just started earning, now is the perfect time to include Term Life Insurance in your Financial Planning strategy. The earlier you begin, the more benefits you'll enjoy over the years.
Don't wait until your responsibilities increase. Compare plans carefully, choose the right Sum Assured, consider valuable Insurance Riders, and invest in a policy that supports your Long-Term Financial Planning while protecting your family's future.
FAQs
1. Why should Gen Z buy term life insurance in their 20s?
In your 20s you get the cheapest premium rate and it stays the same for life. You are healthy so getting policy approval is fast and easy.
2. Do unmarried young adults need term life insurance?
Yes. Many young adults financially support their parents or carry loans. A term plan ensures your family is protected from sudden debt and financial stress.
3. How much term insurance cover should Gen Z buy?
A simple rule is to pick a cover that is 10 to 20 times your yearly income. This formula works for every salary level and ensures your family can manage their daily expenses comfortably without financial stress.
4. Which riders should young buyers add to their plan?
The most essential riders are Critical Illness for major medical expenses, Accidental Death for extra financial support, and Waiver of Premium if disability stops your earnings.
5. What are the biggest mistakes young adults make when buying term insurance?
The most frequent errors are delaying the purchase, picking very low cover just to save on premium, skipping important riders, and not disclosing health details honestly.